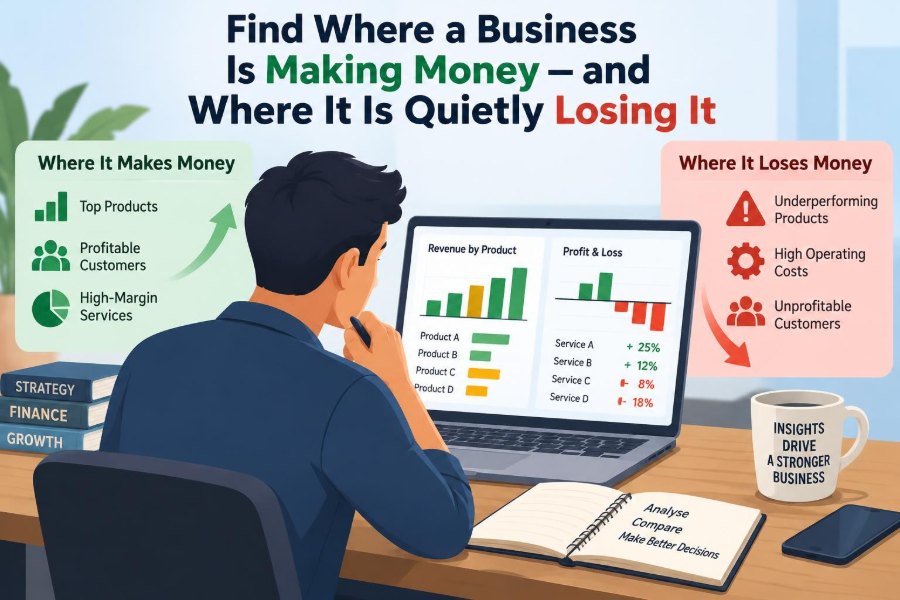

A business can look busy every day and still be headed in the wrong financial direction. Orders are coming in, staff are working hard, and the bank balance may even appear stable. Yet at the end of the month, the owner cannot explain why there is so little left over.
This problem is not limited to small firms. A growing company can hide weak product lines behind a few excellent ones. A retailer can celebrate rising sales while discounts, returns, and delivery costs steadily erode profit. A service business can win impressive clients but lose money whenever its team spends too many unbilled hours serving them.
Finding where a business makes money is therefore more than reading the total sales figure. It means tracing revenue through the costs, time, discounts, and operational choices attached to it.
The goal is not to blame a department, product, or employee. It is to make better decisions with clearer evidence: invest in what creates value, repair what can be fixed, and stop funding losses that have no strategic purpose.
🔎 Start With the Right Question
The useful question is not simply, “What are we selling most?” It is, “What creates cash and profit after the costs required to deliver it?” High sales and high profit are related, but they are not the same thing.
A product with modest sales may produce strong returns because it has a healthy margin and few support needs. Another product may generate much larger revenue but require expensive materials, repeated rework, heavy discounting, and customer service.
💰 Separate Revenue From Profit
Revenue is the money earned from sales before costs are deducted. Profit is what remains after relevant costs have been subtracted. Confusing these measures is one of the quickest ways to misread business performance.
Suppose a hypothetical café sells a £5 sandwich. If ingredients, packaging, payment fees, and direct preparation cost £2.50, the sale contributes £2.50 before rent, manager salaries, and other shared costs. The full £5 is revenue; it is not all available to the business.
🧾 Learn the Main Layers of Cost
Not every cost behaves in the same way, so a useful analysis separates costs into layers. This prevents managers from making decisions based on an oversimplified “sales minus all expenses” calculation.
- Direct costs: costs clearly tied to making or delivering a sale, such as materials, freight, sales commission, or subcontractor time.
- Variable costs: costs that tend to rise as volume rises, including transaction fees and packaging.
- Fixed costs: costs that usually stay similar over a period, such as rent, insurance, or a salaried manager.
- Overhead: shared operating costs that support the business but cannot always be assigned neatly to one sale.
A cost may fit more than one description. For example, hourly production labour can be both direct and variable.
📈 Use Gross Margin as an Early Signal
Gross profit is revenue minus the direct cost of goods or services sold. Gross margin expresses that gross profit as a percentage of revenue. It is an early indicator of whether a sale is economically attractive before broader operating costs are considered.
A falling gross margin deserves investigation even if revenue is growing. Supplier prices may have risen, staff may be taking longer to deliver the work, or sales teams may be offering larger discounts to preserve volume.
Margin should be compared across similar periods and similar offerings. A seasonal product or an introductory offer can have a lower margin for legitimate reasons; the key is knowing whether that trade-off is deliberate.
🧮 Understand Contribution Margin
For many decisions, contribution margin is even more useful than gross margin. It is the revenue remaining after all variable costs associated with a sale are covered. That remaining amount contributes toward fixed costs and, eventually, profit.
Imagine an online seller that receives £100 for an order. Materials cost £35, packaging costs £5, marketplace fees cost £12, and shipping absorbed by the seller costs £10. The contribution is £38. That £38 must help pay salaries, rent, software, marketing, and other overhead.
Contribution margin is particularly valuable when deciding whether to accept extra work, run a promotion, or add a product to spare production capacity.
🗂️ Break Down Results by Meaningful Segments
Company-wide totals can conceal the real story. Break performance into segments that reflect how the business operates: products, services, locations, customer groups, channels, regions, salespeople, or projects.
A clothing retailer might find that in-store sales are profitable while online sales become thin after delivery and returns. A consultancy might discover that one type of project has excellent margins while another regularly exceeds its planned hours.
Choose segments that lead to decisions. There is little value in producing ten different reports if nobody can change pricing, staffing, purchasing, or service design as a result.
🧭 Choose the Right Unit of Analysis
The best unit is the smallest level at which a manager can act without creating misleading detail. For a restaurant, that might be a menu item or a meal period. For a construction firm, it may be an individual project. For a software company, it might be a customer plan or customer cohort.
Too broad, and losses disappear inside averages. Too narrow, and data collection becomes expensive or unreliable. Start with the decisions that matter most, then design measurement around them.
🏷️ Track Discounts, Credits, and Returns
List price is often a poor measure of what a business actually earns. Discounts, rebates, promotional codes, refunds, warranty credits, chargebacks, and returns can materially reduce realised revenue.
A product sold repeatedly at a 20% discount may appear popular in sales reports while contributing much less than expected. If the same item also has a high return rate, its apparent success may be largely an accounting illusion.
Review net revenue: the amount left after reductions from the original sale price. This gives a more honest base for margin calculations.
🚚 Count the Hidden Cost of Fulfilment
Many losses arise after the customer clicks “buy.” Picking, packing, delivery subsidies, damaged goods, rush shipping, installation visits, and failed deliveries all consume resources.
These costs are easy to overlook when they sit in separate expense accounts. Bringing them together by product or channel often reveals why a seemingly successful offer produces weak contribution.
Do not assume every customer expects free delivery or immediate service. Clear service tiers can let customers choose between speed and price while protecting the economics of the order.
⏱️ Measure Time in Service Businesses
In service businesses, time is often the equivalent of inventory. Legal firms, agencies, repair companies, consultancies, and IT providers may lose money not because their rates are too low on paper, but because delivery takes longer than planned.
Track estimated versus actual hours for each project or customer type. Include meetings, revisions, administration, travel, internal review, and support after delivery—not only time that can be billed.
This does not mean treating every minute as a burden. Relationship building and quality checks can be valuable. The point is to know when “small extras” have become a routine, unpriced part of the service.
👥 Identify Profitable and Costly Customer Groups
Large customers are not automatically profitable customers. Some buy often, pay promptly, place predictable orders, and require little support. Others demand customised terms, frequent urgent work, extensive reporting, and long payment periods.
Customer profitability analysis looks at both revenue and the cost to acquire, serve, retain, and support each account. It can be especially revealing where a small group of demanding clients absorbs a disproportionate share of staff time.
The ethical and commercial response is not necessarily to drop difficult customers. It may be to reset scope, charge for premium service, improve onboarding, or decide that the relationship supports a strategic goal.
🛒 Compare Sales Channels Fairly
Direct sales, distributors, marketplaces, retail stores, and websites each carry different economics. A channel with lower headline revenue may produce higher contribution because it avoids commissions, wholesale discounts, or costly returns.
Compare channels after including their distinct costs: advertising, platform fees, sales salaries, trade allowances, customer service, inventory handling, and credit risk. Avoid allocating costs mechanically when a cost clearly belongs to one channel.
| Channel | Possible strength | Often-missed cost |
|---|---|---|
| Direct website | Control over price and customer data | Digital advertising, fulfilment, returns |
| Marketplace | Access to existing demand | Commission, platform fees, price competition |
| Wholesale | Higher volume and simpler order flow | Lower selling price, trade discounts, credit exposure |
| Field sales | Complex relationship selling | Travel, salary, commission, long sales cycle |
📦 Watch Inventory for Silent Losses
Inventory ties up cash before it creates revenue. Slow-moving stock can become obsolete, damaged, unfashionable, expired, or expensive to store. Even if it remains on the balance sheet, it may no longer be worth what the records suggest.
Review inventory ageing: how long products have sat without selling. A pattern of old stock may signal weak forecasting, excessive purchasing, too many variations, or a product that should be discontinued.
Discounting old stock can release cash, but it should be treated as a decision with a cost, not proof that the original purchasing plan worked.
🏭 Examine Waste, Rework, and Quality Failures
Every defective unit, correction, remake, or repeated service visit consumes labour and materials. These costs are often scattered across production, customer service, warranty, and logistics accounts, which makes their combined impact easy to miss.
Track where failures originate. A low-cost component may not be a saving if it causes rework later. Likewise, rushing a task may reduce apparent labour time today while creating expensive returns tomorrow.
Quality improvement is not only about reputation. When aimed at recurring faults, it can directly improve margins by preventing cost rather than merely controlling it.
📣 Treat Customer Acquisition as an Investment
Marketing spend should be connected to the customers and contribution it creates where practical. A campaign that generates many first purchases may still be unprofitable if customers do not return or if acquisition costs are too high relative to margin.
Customer acquisition cost is the cost of gaining a customer through a particular campaign or channel. It should not be assessed in isolation. The relevant question is whether the customer’s expected future contribution justifies the initial spend.
Attribution is imperfect: customers may see several messages before buying. Use reasonable methods consistently, and avoid pretending that one dashboard can assign every sale with certainty.
🔁 Look at Repeat Purchases and Retention
A customer who buys once is different from a customer who returns regularly. Repeat business can improve profitability because the business may spend less on acquisition and can serve familiar customers more efficiently.
However, retention is not automatically healthy. If customers stay only because they receive costly concessions, unlimited support, or underpriced renewals, the relationship may still destroy value.
Review retention alongside margin, service demand, and payment behaviour. The goal is profitable loyalty, not loyalty at any price.
💳 Follow Cash, Not Just Accounting Profit
A profitable sale does not always produce cash quickly. If a business pays suppliers upfront but customers pay months later, growth can strain working capital even when the income statement looks encouraging.
Watch accounts receivable, overdue invoices, inventory levels, supplier terms, and customer deposits. These affect the cash conversion cycle: the time between paying for resources and receiving cash from customers.
Cash flow analysis does not replace profit analysis. It answers a different question: whether the business can fund its operations while it waits for earnings to turn into cash.
📅 Compare Trends Rather Than Isolated Months
One month can be distorted by a large order, a delayed invoice, a seasonal rush, or a one-off repair. Trends reveal whether margins, volume, returns, and operating costs are moving in a sustainable direction.
Compare the current period with prior periods that are genuinely comparable. A seasonal business may need to compare this December with last December rather than with November.
When a figure changes, ask what operational event explains it. A report is a starting point for investigation, not the investigation itself.
🎯 Use Budgets and Forecasts as Decision Tools
A budget sets an expectation for revenue, costs, and resources. A forecast updates that expectation using current information. Both are more useful when they are tied to drivers such as units sold, price, staff hours, material usage, and conversion rates.
If actual margin falls below plan, managers can test possible explanations: lower prices, a higher-cost product mix, supplier increases, or more waste. This is more actionable than simply noting that profit missed budget.
Forecasts should be revised when conditions change. Treating an old budget as fixed truth can delay necessary decisions.
🧩 Distinguish Product Profitability From Portfolio Value
Not every item must earn the same margin. A low-margin product can bring customers into a store, support sales of higher-margin items, complete a credible range, or protect an important relationship.
That does not make it harmless. The business should be explicit about its role and set limits on the subsidy it is willing to provide. A product kept for strategic reasons should be reviewed like any other investment.
Portfolio decisions require judgment. Removing every low-margin item may simplify operations but could also reduce traffic, choice, or cross-selling opportunities.
⚖️ Allocate Overhead Carefully
Overhead allocation assigns shared costs, such as rent or management salaries, to products, customers, or departments. It can help show the full economics of an area, but allocations can also create false precision.
For example, allocating rent solely by sales revenue may make a high-priced, low-space product look more costly than it really is. Allocating warehouse costs by pallet space or handling activity may be more meaningful.
Use allocations to understand long-term sustainability, but do not let an arbitrary allocation obscure short-term contribution decisions. The cost of an empty office does not disappear simply because one small order is rejected.
🛠️ Use Activity-Based Thinking for Complex Operations
Activity-based costing links overhead to the activities that cause it, such as purchase orders processed, deliveries made, machine setups, support tickets handled, or invoices issued. It can reveal that small, frequent, customised orders are much more expensive than large standard ones.
A full activity-based system may be unnecessary for a small business. The underlying idea is still useful: identify the operational activities that drive cost, then measure them well enough to improve decisions.
Start with the biggest suspected distortions rather than attempting to map every minor expense.
🚦Find the Break-Even Point
The break-even point is the level of sales at which total contribution covers fixed costs, leaving neither profit nor loss. It helps managers understand the volume required for a product, project, or business to support itself.
If fixed monthly costs are known and each sale contributes a reasonably stable amount, break-even analysis can be straightforward. In reality, prices and costs may vary, so use ranges and scenarios instead of treating one calculation as a guarantee.
Break-even analysis is especially useful before adding capacity, opening a location, hiring staff, or launching an offer with substantial fixed commitments.
🔍 Investigate Variances With Curiosity
A variance is the difference between expected and actual performance. A negative variance is not automatically a failure; it is a prompt to understand what happened.
Ask focused questions: Did unit cost rise because a supplier changed price? Did labour hours increase because of training, poor scheduling, or a more complex product mix? Did revenue fall because volume dropped, prices changed, or customers bought different items?
Blaming people too quickly makes reporting less honest. A useful review combines financial data with the operational knowledge of the people doing the work.
🧠 Avoid the Most Common Analytical Traps
Several habits repeatedly produce misleading conclusions:
- Judging success by revenue alone.
- Using average margins that hide loss-making products or customers.
- Ignoring returns, support, delivery, and rework.
- Assigning every fixed cost to a short-term decision without considering whether the cost will actually change.
- Collecting detailed data that is inaccurate, late, or never used.
- Cutting costs that protect quality, retention, or compliance without understanding the consequences.
Good analysis is not the most complicated spreadsheet. It is the clearest reliable view that leads to better action.
🗣️ Combine Numbers With Frontline Insight
Financial reports can show where a problem appears, but frontline teams often know why it appears. Sales staff may know which customers request costly exceptions. Operations staff may see a bottleneck that creates overtime. Customer service may recognise a product that generates repeat complaints.
Create a regular process for comparing the numbers with operational reality. This improves both the quality of data and the practicality of proposed solutions.
It also reduces the risk of managers imposing a financially neat change that creates service problems elsewhere.
📊 Build a Simple Profitability Dashboard
A dashboard should make patterns visible, not overwhelm readers. For each priority segment, include a small set of measures that link sales to economic outcomes.
- Net revenue and sales volume
- Gross or contribution margin
- Discounts, returns, and credits
- Direct labour or fulfilment cost
- Customer acquisition or channel cost where relevant
- Inventory ageing, overdue debt, or project hours where relevant
Show trends and compare actual results with a realistic plan. Add short notes explaining significant movements so decision-makers do not have to guess.
🗓️ Create a Regular Review Rhythm
Profitability analysis works best as a routine, not an emergency exercise when cash is already tight. A monthly review may suit many businesses, while fast-moving operations might track selected indicators weekly.
Use a consistent sequence: prepare accurate data, identify major changes, investigate drivers, decide actions, assign owners, and revisit outcomes. Without the final step, reports become observations rather than management tools.
Not every movement needs a meeting. Focus attention on material changes, persistent trends, and areas where a decision is possible.
🔧 Turn Findings Into Specific Actions
Once a loss source is understood, the response should match the cause. Raising prices may help when value is underpriced, but it will not fix poor scheduling. Cutting marketing may improve short-term expenses while weakening a profitable customer pipeline.
Possible actions include:
- Renegotiating supplier terms or redesigning a product to reduce direct cost.
- Setting minimum order values, delivery fees, or service tiers.
- Improving estimates, scope control, and time tracking on projects.
- Removing a recurring cause of returns or rework.
- Adjusting prices, discount authority, or sales incentives.
- Stopping, redesigning, or deliberately retaining an offer for a stated strategic reason.
State what result is expected and how it will be measured. Otherwise, a change can feel productive without improving the underlying economics.
🌱 Protect Value While Improving Profit
The aim is not to minimise every cost. Some spending creates value: skilled employees, reliable materials, thoughtful customer support, quality control, and useful technology can strengthen long-term performance.
The better question is whether a cost produces enough value for customers and for the business. Reducing a support team may lower expenses this quarter but increase cancellations, complaints, and expensive recoveries later.
Profitability improvement is strongest when it removes waste, clarifies choices, and aligns price with the service actually delivered.
🧭 The Core Principle: Follow the Economics of Each Decision
Businesses make money where customers pay enough, often enough, and promptly enough to cover the resources required to serve them. They quietly lose money where hidden costs, unpriced effort, weak processes, or poor assumptions consume more value than the sale creates.
The most reliable approach is to move from totals to drivers. Examine net revenue, direct and variable costs, time, quality, channel economics, customer behaviour, and cash timing. Then connect those findings to decisions that teams can actually make.
Numbers do not replace judgment, but they make judgment more disciplined. They help managers distinguish a temporary issue from a structural weakness, and a strategic investment from an unnoticed subsidy.
A business becomes easier to improve when every major source of revenue can be traced to the work, cost, and cash required to create it. Clear visibility turns financial management from a backward-looking report into a practical guide for better choices. 📊💡